Sudden and accidental damage
Standard homeowners policies often cover water damage that happens suddenly, like a burst pipe or a failed supply line. Your policy decides.
Damage to the house and damage to your belongings may fall under different parts of the policy. The repair to the pipe itself may be treated separately from the water damage it caused.
Slow leaks and wear
Damage from a leak that went on for weeks or months, or from wear and lack of maintenance, is often excluded. Carriers look at how long it lasted.
That’s one reason to act on a small leak quickly and write down when you found it.
Flooding from outside
Damage from rising water outside your home usually needs separate flood insurance, such as a policy through the National Flood Insurance Program.
Storm water that comes in through a damaged roof or window can be treated differently from rising flood water. Ask your agent how your policy handles each.
Sewer and drain backups
Sewer and drain backup coverage varies. Some policies include it and others add it with an endorsement. Your agent can tell you which you have.
What to document
Photograph the damage before moving anything, keep damaged items until your adjuster says otherwise, and save receipts for what you buy.
Write down when you found the water and what you did to stop it. If you bought fans or supplies, or had to stay somewhere else, keep those receipts too.
Don’t wait to stop the damage
Many policies ask you to take reasonable steps to prevent further damage. Removing water and starting to dry promptly is part of that.
Check with your carrier if you’re unsure, but don’t leave standing water while you wait for an adjuster.
How we help with your claim
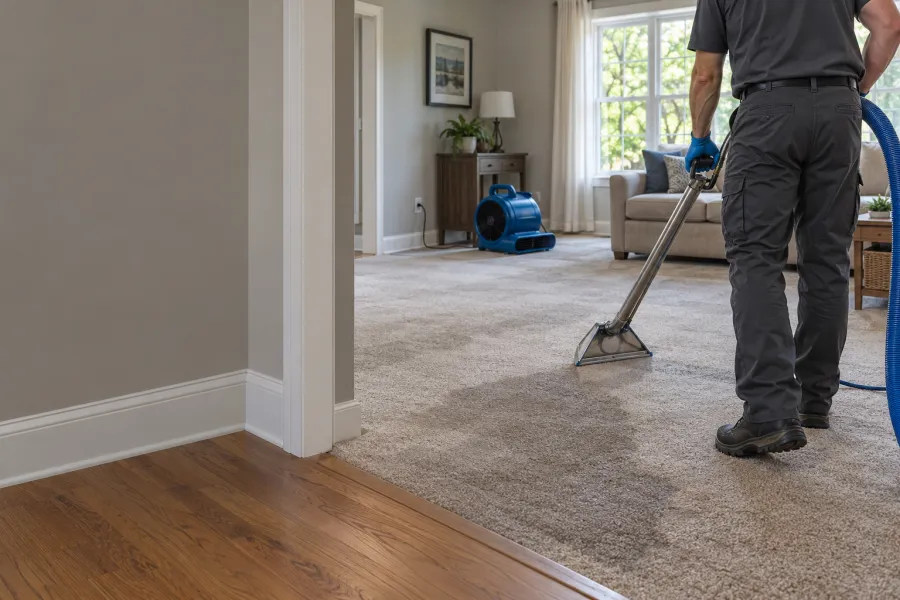
We document the loss with photos, moisture readings and drying records and share them with your adjuster. We don’t decide coverage.
Read more about how a claim works with United. This guide is general information, not advice about your policy. Your agent and carrier can tell you what your policy covers.